Cash-in split across agents
Five agents, one wallet, each deposit just under the reporting threshold, all inside 24 hours.
AML & fraud monitoring · West Africa
Stop fraud before the money moves.
Find laundering hidden across months.
Close every case with evidence.
The problem
Millions of small payments a month. Threshold reports bury the few that matter.
Split cash-in, SIM swaps, wallets used as pass-throughs. Rules built elsewhere don’t look for them.
Not “we reviewed it”. What the rule saw, who decided, who approved, and when.
How it works
The report your MLRO signs traces back to the exact data and rule version behind it.
Arrives by API. Encrypted on arrival. Stored as evidence.
Versioned rules check it against 180 days of history.
Hits merge per customer. Approved suppressions apply.
One case, one owner, an SLA and an uneditable timeline.
An STR drafted from the case, approved by a second person.
Real time
Your switch asks before it authorises. The answer comes back with reasons.
Post-event & scheduled
Rules look back across 180 days without touching your core banking system.
Built for how West Africa moves money.
Mobile money wallets · agent networks · instant bank transfers · USSD
Market packs
Every market has its own pack. Shown here: Ghana’s gh-psp, with the patterns behind mobile money and agent fraud. Nigeria and the UEMOA states have theirs.
Five agents, one wallet, each deposit just under the reporting threshold, all inside 24 hours.
A new SIM, a reset PIN and a large transfer to a new payee within minutes. Stopped before the money leaves.
Dozens of small payments in, a few large ones out, the balance back near zero within a day.
Illustrative figures. Thresholds are calibrated with each institution.
The product
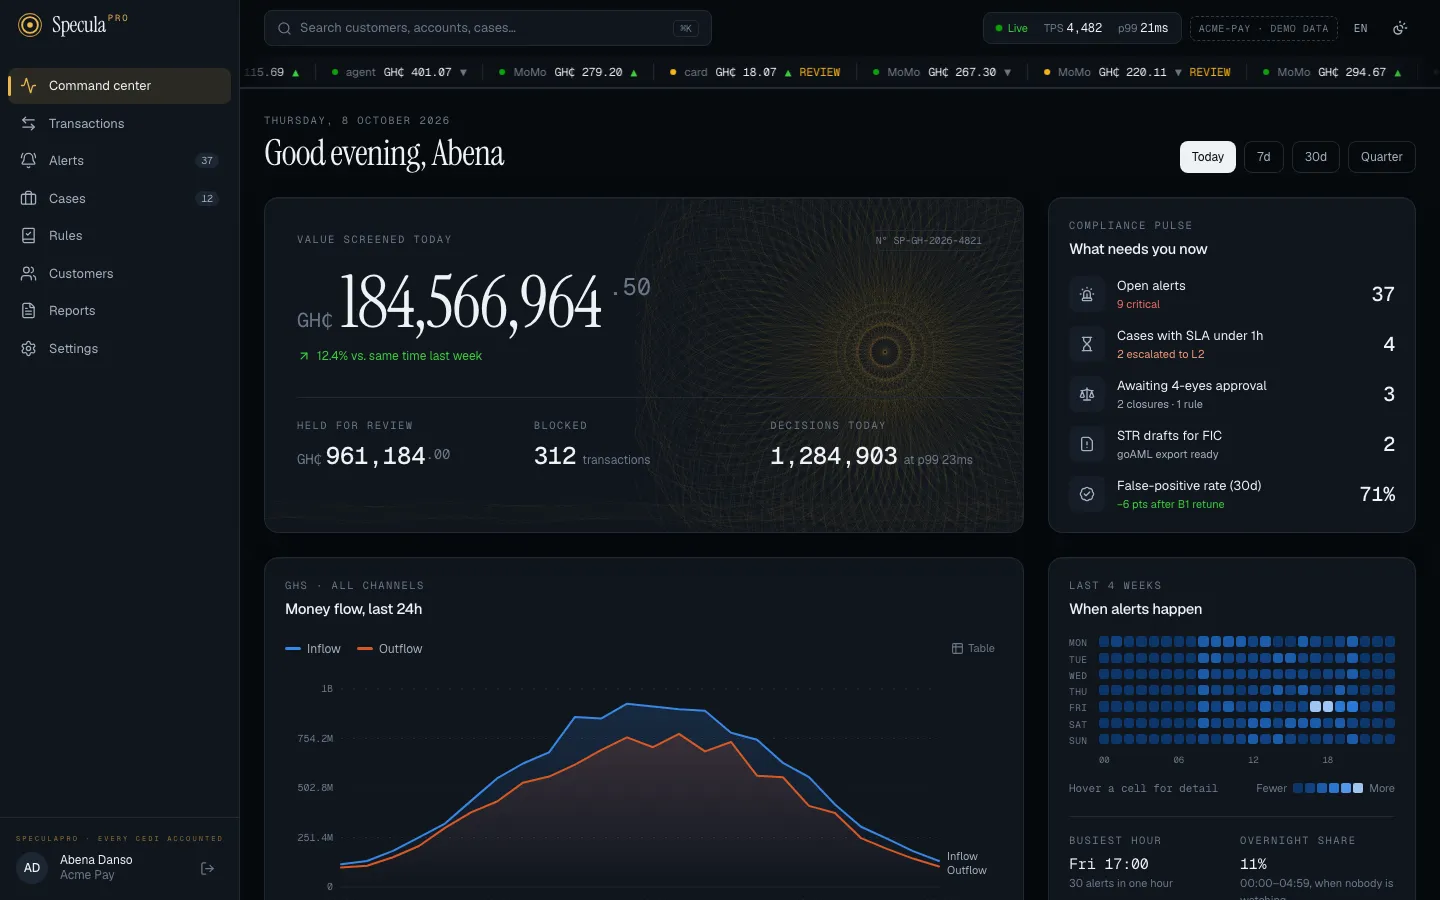
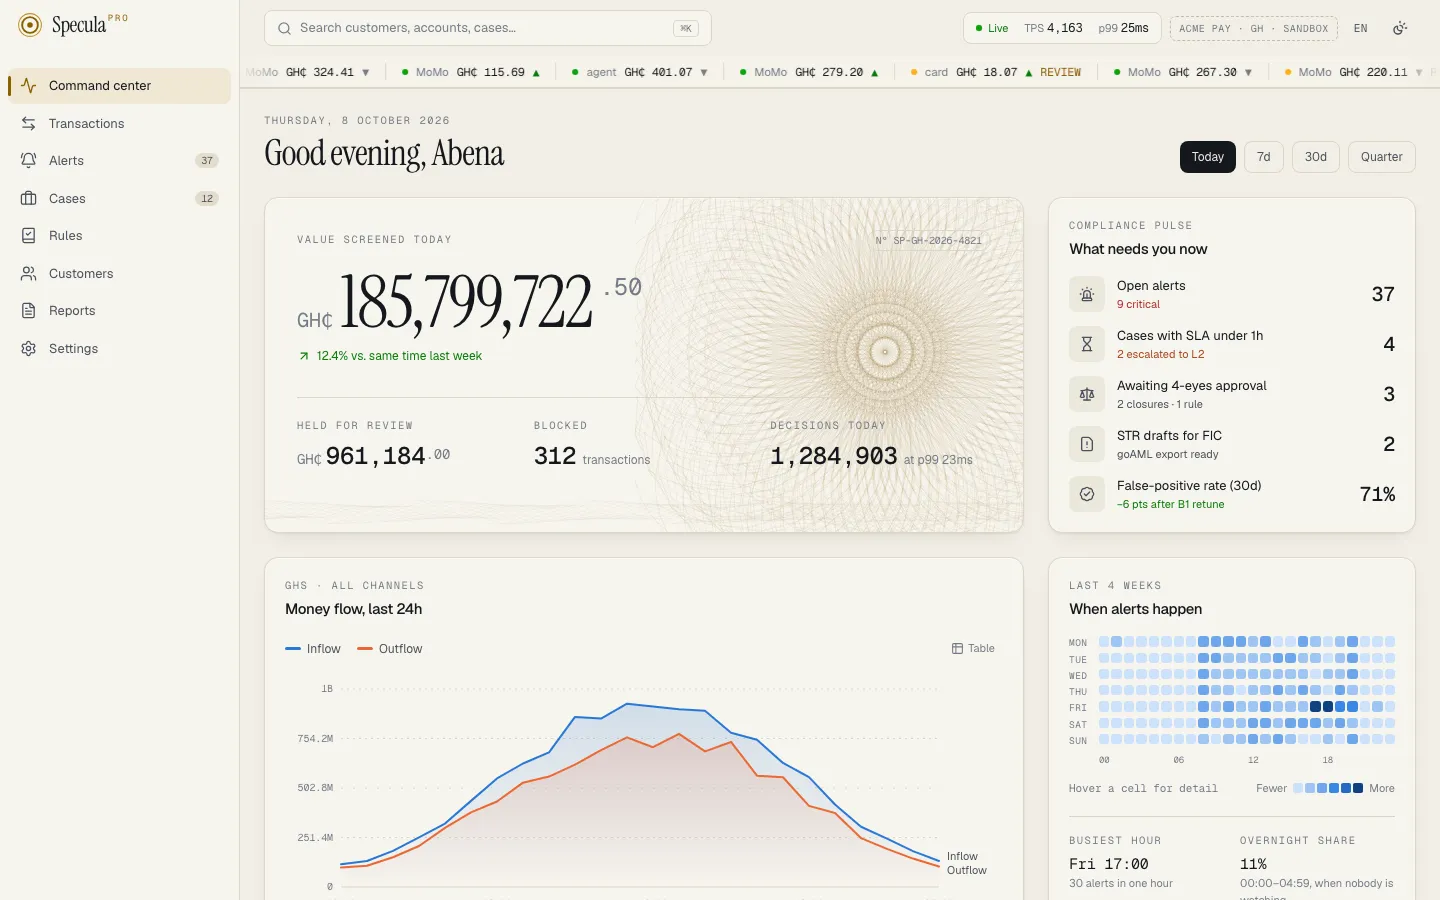
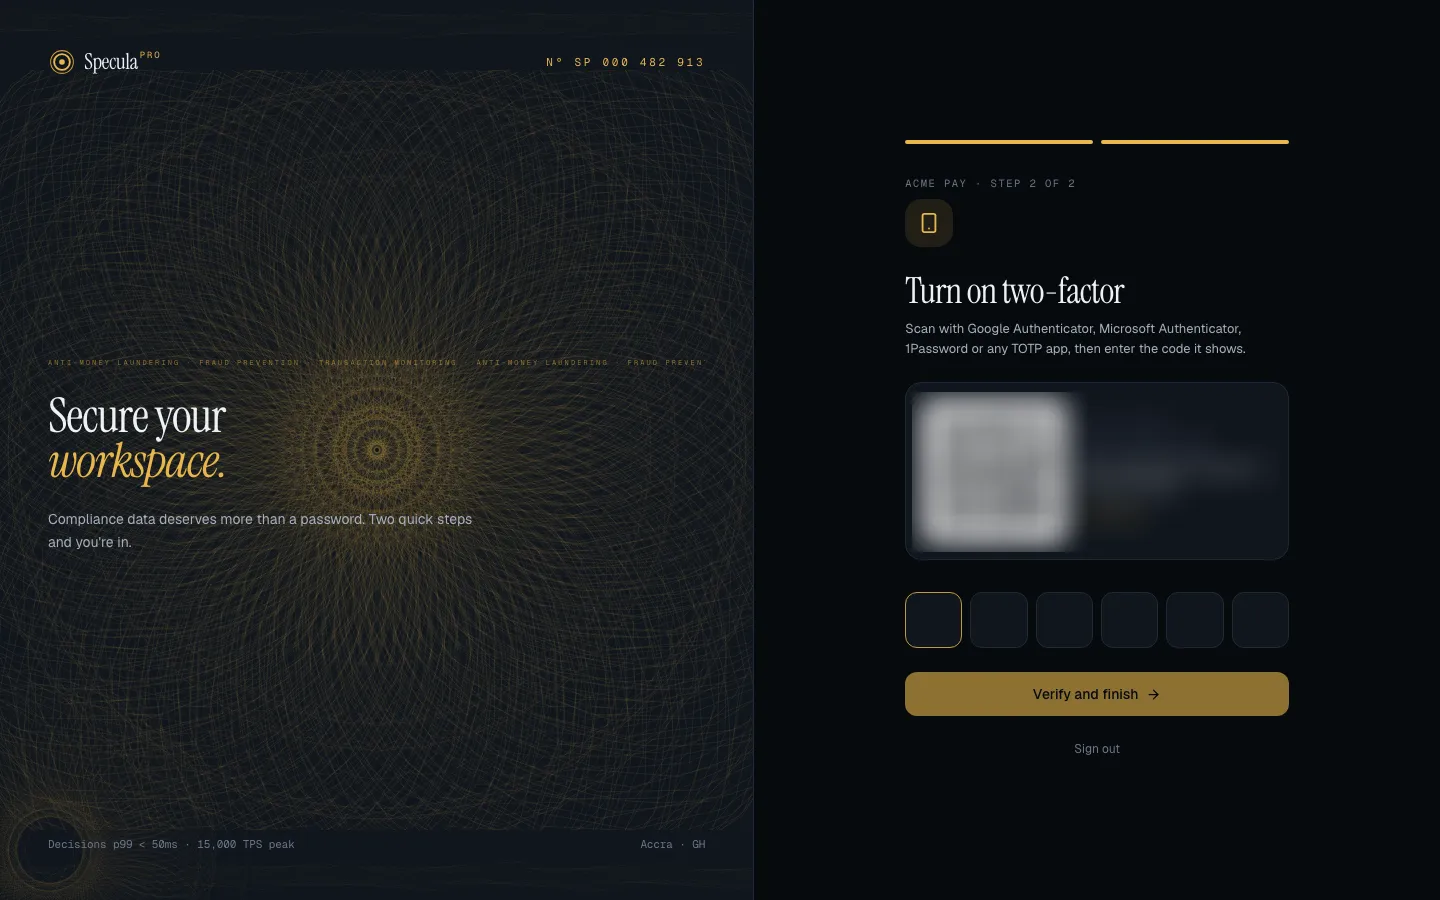
Live decisions, the compliance pulse and every open case on one screen. Two-factor sign-in from day one.
See every feature →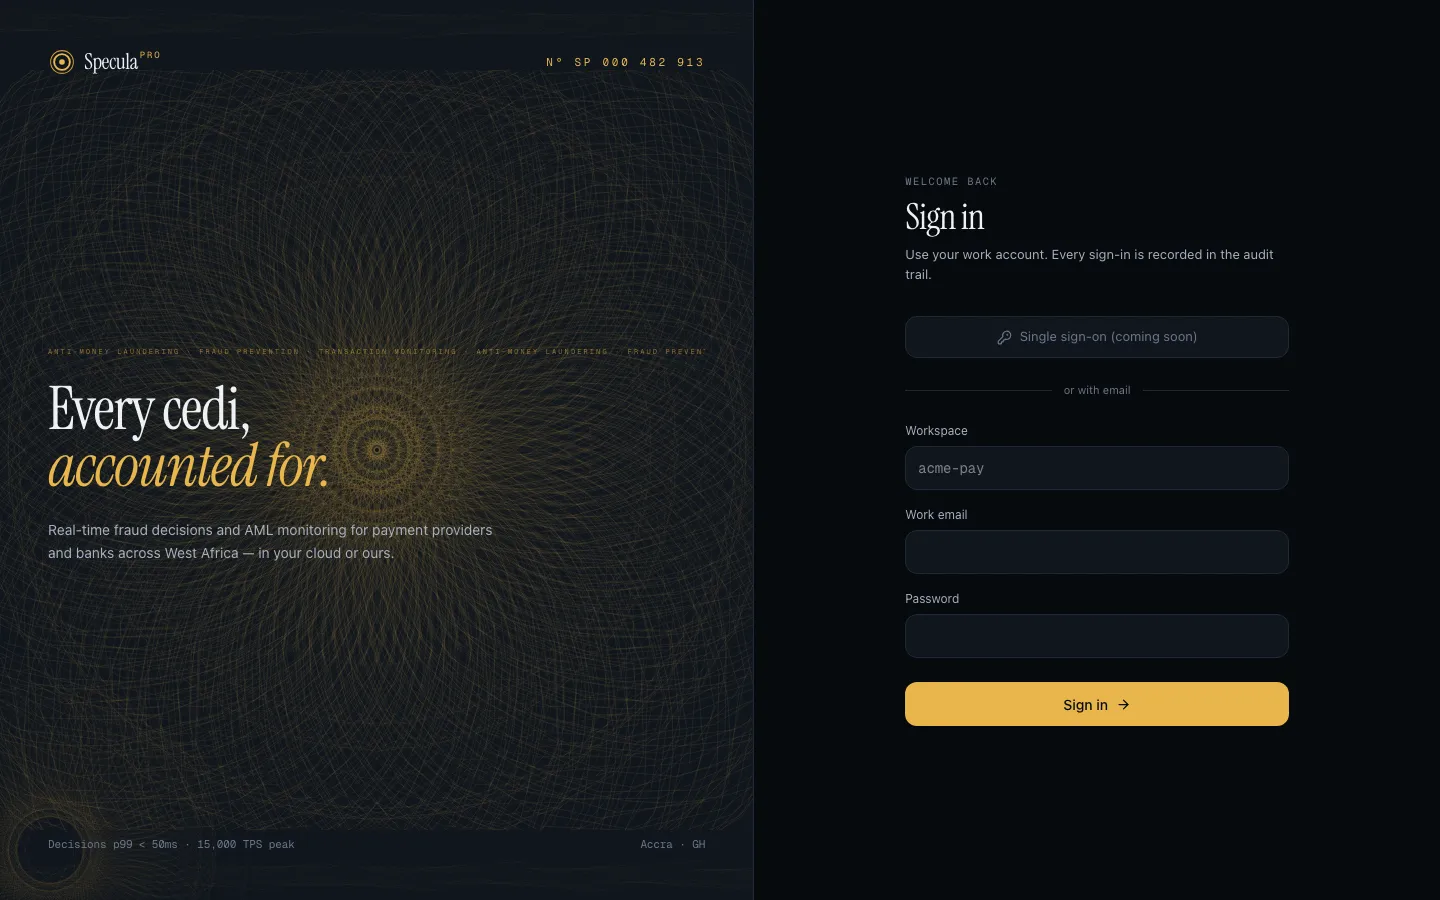
Want to see it on your own data?
Book a walkthrough →Rule library
Change a threshold without a release. Every change versioned, and approved by a second person.
Large cash, cross-border, KYC tier limits
Deposits just below a threshold, split across agents
Spikes against the customer’s own profile
Fan-in, fan-out, circular flows, shared devices
High-risk jurisdictions, impossible travel
PEPs, sanctioned parties, deny-lists
Agent anomalies, cash-out after cash-in, SIM swap
Card testing, account takeover, new device and payee
Turnover far above declared, refund abuse
Nineteen packs today: core (24 rules), fraud (11), global-fatf (8), Ghana (gh-psp 14, gh-bank 10), Nigeria (ng-psp 9, ng-bank 8), the UEMOA (uemoa-emi 8, uemoa-bank 8), and two packs each for Sierra Leone, Liberia, The Gambia, Guinea and Kenya (86 rules between them), with some rules shared within each pair. The figures in those last five countries' packs come from our research and are still to be verified with counsel and each regulator. Thresholds are calibrated with each institution before go-live.
Security & data residency
Engineering targets
Targets the platform is engineered and tested against. We confirm them against your real volumes during a pilot; they are not measured production figures.
Next step
Tell us about your institution, your volumes and your regulator. We’ll show you the platform and talk about a pilot.